What happened The piece shows how rising pay can be swallowed by spending, debt and poor saving habits, and offers habits to protect wealth.
Why it matters Builders need to turn pay rises into financial security, not just a bigger monthly bill.
What to do Before a raise, decide how much to save or use for debt; track all expenses for a month; set a realistic savings target and automate it.
Your salary increases, but your savings do not, highlighting the need for balancing your earnings and savings while you learn to manage lifestyle inflation Nigeria‑style and discover how debt and everyday financial decisions can shape your long‑term financial future.
Imagine two people earning ₦250,000 a month.
One spends almost everything on rent, transport, food, subscriptions and social outings. The other covers essential expenses, saves what they can, manages debt carefully and gradually builds an emergency fund.
Now imagine that both receive a pay rise. One immediately upgrades their lifestyle, while the other directs part of the additional income towards savings, debt repayment and future goals.
Over time, their financial positions could look very different, even if they started with similar salaries.
The difference is not necessarily how much they earn. It is how they manage what comes in.
Earning more gives you more financial possibilities, but what you do with that money determines how much of it you keep and build upon.
The Lifestyle Inflation Trap
Lifestyle inflation happens when your spending increases alongside your income.
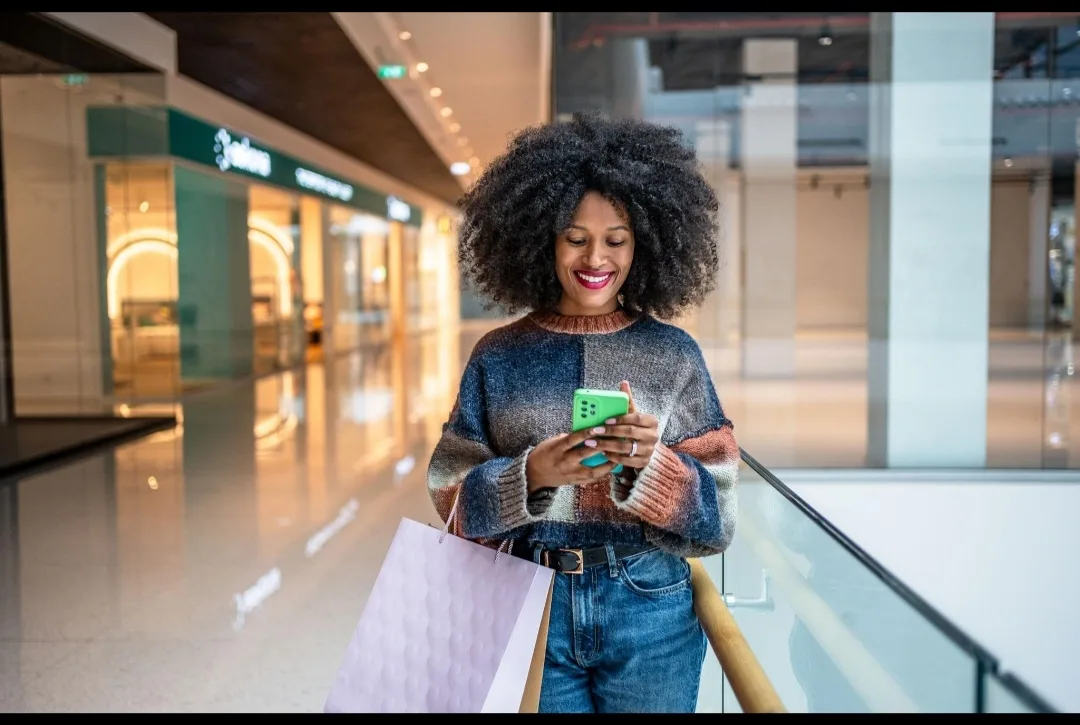
DailyA young African woman carries shopping bags while using her phone, illustrating lifestyle spending.
A better salary might mean moving into a more expensive apartment, buying a newer phone, eating out more often or upgrading your wardrobe. There is nothing inherently wrong with enjoying the rewards of your hard work.
The problem begins when every increase in income brings a matching increase in expenses.
Suppose your monthly income rises from ₦200,000 to ₦300,000. You now earn an additional ₦100,000. But if your spending also increases by ₦100,000, you have gained earning power without creating any additional room for savings.
You may feel richer while remaining just as financially stretched.
Do this week
Write down where any extra ₦100,000 will go before you receive it
Automate a transfer of at least 10% of any raise into savings
List all current debts with interest rates and minimum payments
3 weeks, one short task a weekday: talk to real customers, test an offer, build the case. ₦5,000 to join.
Join the challenge
One way to avoid this is to decide what you will do with extra income before you receive it. You could direct a portion towards savings, debt repayment or a long‑term goal before increasing your discretionary spending.
You do not have to deny yourself every comfort. The aim is to enjoy your money without allowing every pay rise to create new financial obligations.
Debt Can Eat into Your Progress
Debt is not always a bad financial decision. Depending on the circumstances, borrowing may help someone pay for education, acquire productive equipment or manage an important expense.
DailyAn African couple reviews household bills and calculates expenses to manage their monthly financial commitments.
However, debt becomes difficult to manage when repayments consume too much of your income or when you repeatedly borrow to maintain a lifestyle you cannot comfortably afford.
Consider someone who earns a good salary but has several loan repayments due every month. By the time the salary arrives, much of it is already committed.
Despite earning well, that person may have little left for emergencies, savings or future plans.
If you have outstanding debt, start by listing what you owe, the interest rates, minimum payments and due dates. This gives you a clearer picture of your obligations and helps you plan repayments realistically.
High‑interest debt deserves particular attention because the interest can make borrowing increasingly expensive. Depending on your circumstances, paying it down may be a more sensible priority than putting additional money into investments with uncertain returns.
Be cautious about borrowing repeatedly to cover routine expenses. If this keeps happening, review your spending, income and financial commitments to understand what is causing the shortfall.
Saving Should Not Depend on What Is Left Over
Many people plan to save whatever remains at the end of the month. Unfortunately, after bills, family responsibilities and unexpected expenses, there may be very little left.
A more deliberate approach is to include saving in your financial plan from the beginning.
Start by tracking your income and expenses for a month. Include small purchases, recurring subscriptions and other costs that are easy to overlook. You may find that some expenses take up more of your income than you realised.
Then choose a realistic savings target. If your income is irregular, you may need to save according to what you earn rather than commit to a fixed monthly amount.
An emergency fund is a useful starting point. It can help you handle unexpected expenses, such as urgent repairs or a temporary loss of income, without immediately relying on expensive borrowing.
Build it gradually. If your finances allow, set aside a manageable amount whenever you receive income. You can increase it as your circumstances improve.
The goal is not to save an impressive amount overnight. It is to build a financial cushion that makes unexpected situations easier to manage.
Building Wealth Requires a Longer View
Saving helps you prepare for expenses and emergencies. Building wealth may also involve investing towards longer‑term goals, such as education, home ownership, business development or retirement.
Before investing, consider when you will need the money, how much risk you can tolerate and whether you can afford to leave the funds invested.
Take time to understand how an investment works, what fees it involves and how you could lose money. Verify providers through the relevant Nigerian regulatory authorities, and be wary of schemes promising unusually high or guaranteed returns.
You do not have to understand every investment product at once. Start by learning the basics and making decisions you can explain and afford.
Building wealth is rarely about finding a shortcut. It is about making informed financial decisions consistently over time.
Four Habits That Can Help You Build Wealth
Give your money a purpose. Plan for essential expenses, savings, debt repayment and the things you enjoy.
Save part of every income increase. When your earnings rise, consider directing some of the additional money towards your financial goals before increasing your spending.
Keep track of your debt. Know what you owe, how much it costs and how you intend to repay it.
Think beyond the next payday. Before taking on a major expense, consider whether it fits your budget and leaves you enough room to handle unexpected costs.
These habits may seem simple, but they can help you make more intentional decisions about your finances.
Your Financial Reality Matters, Too
It is important to recognise that not everyone earns enough to save comfortably. Rising living costs, unstable employment, family responsibilities and unexpected expenses can make financial planning difficult.
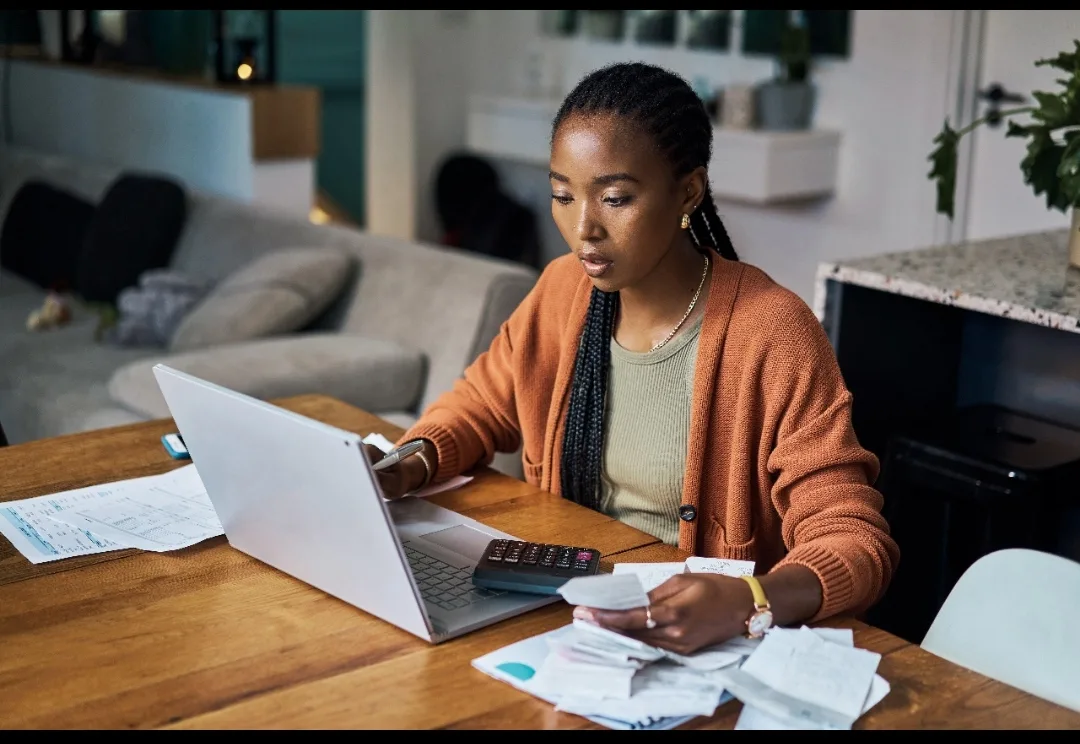
DailyAn African woman reviews her finances at a desk, using a laptop and calculator while examining cash, bills, and financial documents.
When your income barely covers necessities, the immediate priority may be meeting essential needs, improving your earning opportunities or managing urgent obligations.
Financial hardship is not always the result of poor decisions, and building wealth is not simply a matter of discipline. Your circumstances and starting point matter.
Still, whenever your finances allow, small and consistent steps can help you create greater stability.
Let Your Money Work Towards Something
The next time your income increases, pause before deciding how to spend the extra money.
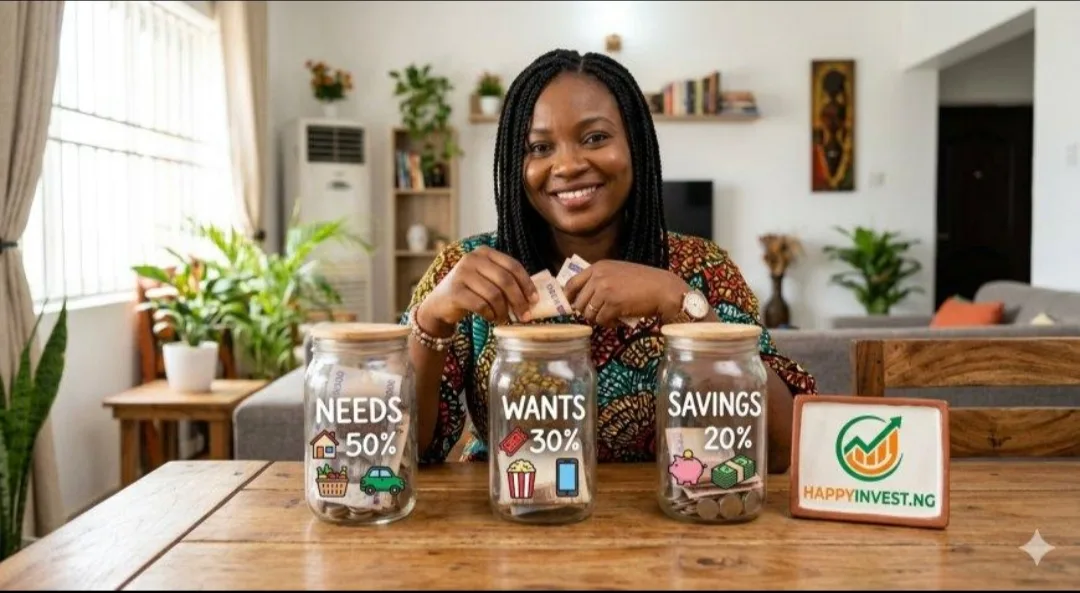
DailyA Nigerian woman puts money aside to build savings and prepare for future expenses.
Ask yourself:
How much can I put aside?
Is there debt I need to reduce?
What future goal can I move closer to achieving?
You do not have to stop enjoying your money. You simply need to make room for both the life you want today and the security you want tomorrow.
“A higher income can create more opportunities, but it does not automatically create financial freedom.”
The goal is not just to earn more. It is to build a financial life that gives you greater stability, more choices and room to grow.
Talk to someone who’s done this
Book a 1:1 call with an expert who has solved this before.