What happened Nigerian earners often see their salary disappear within two weeks despite budgeting advice.
Why it matters Understanding where money goes helps builders avoid cash‑flow crises and plan sustainable finances.
What to do Create a simple budget, allocate funds to essentials and savings first, and review spending each week to stay on track.
Getting paid is one thing; learning how to stretch your salary and make it last is another. Discover practical ways to manage your income, plan for important expenses, save consistently and avoid running out of money before your next payday.
Dear salary earner,
That alert you've been waiting for finally arrives. Your salary is in!
For a moment, everything feels possible. You can pay your bills, settle outstanding debts, buy a few things you've been putting off and perhaps even treat yourself. After all, you've worked hard for the money.
But fast-forward two weeks. You check your account balance, and one question comes to mind: Where did all the money go?
Your rent is still waiting. Transport expenses haven't stopped. Food prices keep rising, and there are still a few people expecting you to remember them.
If this sounds familiar, you're not alone.
One of the biggest financial challenges many salary earners face is not necessarily how much they earn, but how they manage the money they receive. Without a clear plan, even a reasonable salary can disappear into expenses long before the next payday.
So, before your next salary alert arrives, here are six practical ways to make your money work better for you.
1. Give Your Salary a Job Before Spending It
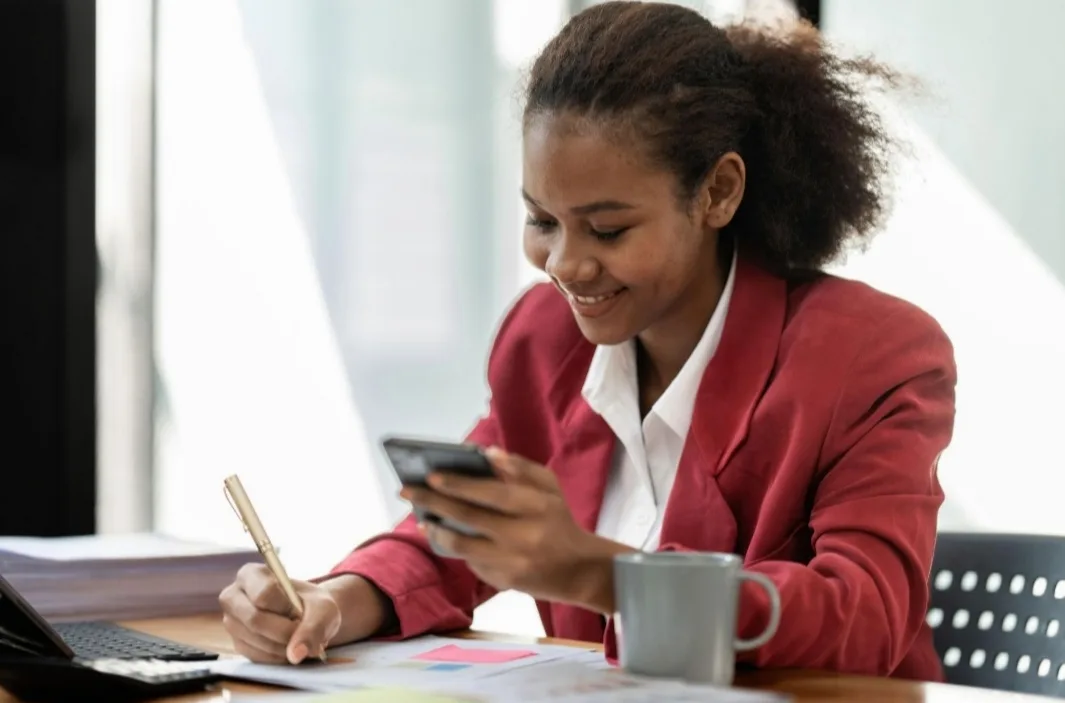
Dailyperson using a smartphone and calculator to review personal finances and manage expenses.
Imagine receiving your salary and immediately starting to spend without knowing how much you need for essential expenses.
You pay for lunch, order something online, send money to a friend and make a few purchases simply because you feel you can afford them.
Before you realise it, a significant part of your income is gone.
This is why budgeting matters.
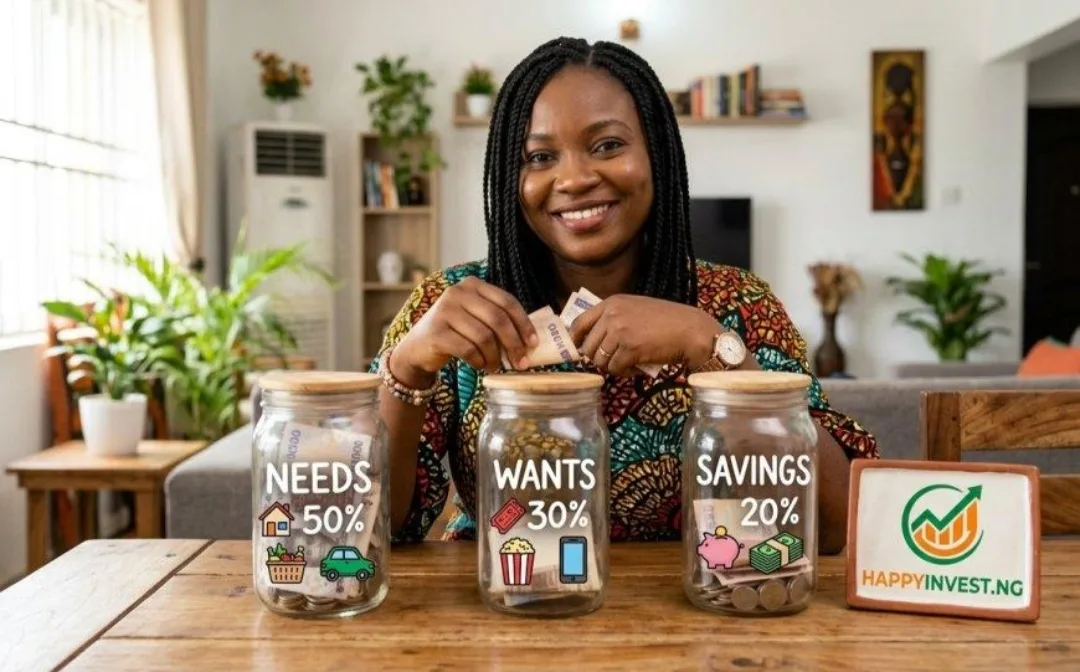
A budget helps you decide what your money should cover before you start spending it. Rather than waiting until the end of the month to see what remains, you assign specific amounts to your needs, savings and personal expenses.
For example, if you earn ₦200,000 monthly, you could divide your income into categories such as:
“You do not have to get everything right in one month. Financial discipline develops through small decisions that you repeat over time.”
Do this week
Write down your expected income and allocate amounts to rent, food, transport, savings and debt before you spend anything.
Open a separate savings account and set up an automatic transfer of at least ₦5,000 each month.
Spend 15 minutes this weekend reviewing your bank statements to spot unnecessary purchases.
Your actual allocation will depend on your responsibilities, location and financial commitments. The important thing is to create a plan that reflects your financial reality.
What to do: Write down your expected monthly income and expenses. Allocate money to your major expenses before you start spending, and leave room for unexpected costs where possible.
2. Stop Treating Every Salary Increase as Extra Spending Money
DailyAn African woman writing a monthly budget and calculating expenses.
Getting a salary increase is exciting. You finally have a little more money to work with, and naturally, you may want to improve your lifestyle.
Perhaps you want a better apartment, a more expensive phone, more frequent restaurant visits or additional subscriptions.
There is nothing wrong with enjoying the rewards of your hard work. However, problems arise when every increase in income comes with an equally large increase in spending.
This is known as lifestyle inflation.
For instance, someone who previously managed on ₦150,000 may start earning ₦250,000 but still struggle financially because their expenses have increased alongside their income.
The additional money that could have gone into savings, investments or debt repayment is now being used to maintain a more expensive lifestyle.
What to do: Whenever your income increases, consider directing part of the additional money towards savings, investments or outstanding financial obligations before increasing your spending.
You deserve to enjoy your earnings, but your future financial stability deserves attention too.
3. Build an Emergency Fund Before Life Surprises You
DailyA person putting money into a savings jar to build an emergency fund.
Let's be honest: unexpected expenses have a way of showing up when you least expect them.
Your phone could develop a fault. You may need urgent medical attention. A family member might need financial assistance, or you could suddenly face an unexpected travel expense.
Without savings set aside for emergencies, you may have to borrow money, use funds meant for important bills or start the month under financial pressure.
This is why an emergency fund is important.
An emergency fund is money you set aside specifically for unexpected expenses. It is not meant for shopping, celebrations, holidays or routine spending.
You do not have to save a huge amount immediately. Start with what you can comfortably afford and build consistently.
For example, you could begin by setting aside ₦5,000 or ₦10,000 monthly. As your income and financial situation improve, you can gradually increase the amount.
Over time, work towards building enough savings to cover several months of essential living expenses.
What to do: Open a separate savings account or use a reliable savings platform to keep your emergency money separate from the funds you use for everyday spending. Make sure you can access it when a genuine emergency arises.
4. Be Careful With Borrowing and Buy-Now-Pay-Later Offers
DailyAn African man worrying about the loan he has to pay.
Sometimes, your salary may not be enough to cover everything you want or need. This can make borrowing seem like an easy solution.
From instant loan applications to buy-now-pay-later services, accessing credit has become increasingly convenient.
But convenience does not always mean affordability.
Before taking a loan, ask yourself a few questions:
Do I genuinely need this money?
Can I afford the repayments?
What are the interest charges and additional fees?
Will repaying this loan affect my ability to cover essential expenses?
For instance, borrowing money to purchase a new phone when your current one works perfectly may create an unnecessary financial burden.
An even bigger problem arises when you take one loan to repay another. This can create a cycle of borrowing that becomes increasingly difficult to escape.
Credit can be useful when managed responsibly, but it should not become a regular solution to poor budgeting or unnecessary spending.
What to do: Understand the full repayment terms before borrowing. Check the interest rate, additional charges and repayment dates. Avoid taking loans simply because they are available, and prioritise paying off expensive debts.
5. Pay Yourself First, Even If Your Salary Is Small
DailyAn African woman putting money aside as part of her monthly savings plan.
Many people save whatever remains after paying their bills and handling personal expenses.
Unfortunately, there is often very little left.
One way to change this habit is to pay yourself first.
This means setting aside a portion of your income for savings as soon as your salary arrives, rather than waiting until the end of the month.
You do not need to start with a large amount. What matters is consistency.
If you can save ₦5,000 monthly, start there. If your financial situation allows you to save ₦20,000, make that your starting point.
You can also automate your savings through your bank or a suitable savings platform so that the money is transferred before you have the chance to spend it.
Remember, saving is not only for people who earn high salaries. It is a habit you can develop at different income levels.
What to do: Choose a realistic savings target and treat it like an important monthly bill. Increase the amount gradually as your financial situation improves.
6. Review Your Spending Before the Next Payday
DailyAn African woman reviewing her expenses before payday.
You cannot improve what you do not pay attention to.
Sometimes, the money you struggle to account for is not going towards one major expense. It disappears through several small purchases that seem insignificant at the time.
Think about the daily snacks, unnecessary subscriptions, frequent food deliveries, impulse purchases and other routine expenses that add up over the month.
You may be surprised by how much these purchases cost when you calculate them.
This does not mean you should stop enjoying yourself or feel guilty about every purchase. It simply means you should understand where your money goes.
At the end of each week, take a few minutes to review your transactions.
Ask yourself:
What did I spend the most money on?
Which expenses were necessary?
What purchases could I have avoided?
Did I save the amount I planned to save?
What can I do differently next month?
What to do: Review your bank statements and spending records regularly. Identify expenses you can reduce and use what you learn to make better financial decisions in the following month.
Your Salary Should Do More Than Help You Survive Until Payday
DailyAn African couple discussing their monthly household budget.
Earning money is important, but learning how to manage it is equally important.
You may not be able to control every expense, especially when prices keep changing and financial responsibilities continue to grow. However, you can become more intentional about how you spend, save and plan.
Start with a budget. Be thoughtful about lifestyle changes. Build an emergency fund, borrow responsibly, save consistently and pay attention to your spending habits.
You do not have to get everything right in one month. Financial discipline develops through small decisions that you repeat over time.
And remember, the goal is not to deny yourself every enjoyment. It is to enjoy what you earn without constantly worrying about how you will manage until your next salary arrives.
So, when your next salary alert arrives, what will you do differently?
Talk to someone who’s done this
Book a 1:1 call with an expert who has solved this before.